PythonQuant
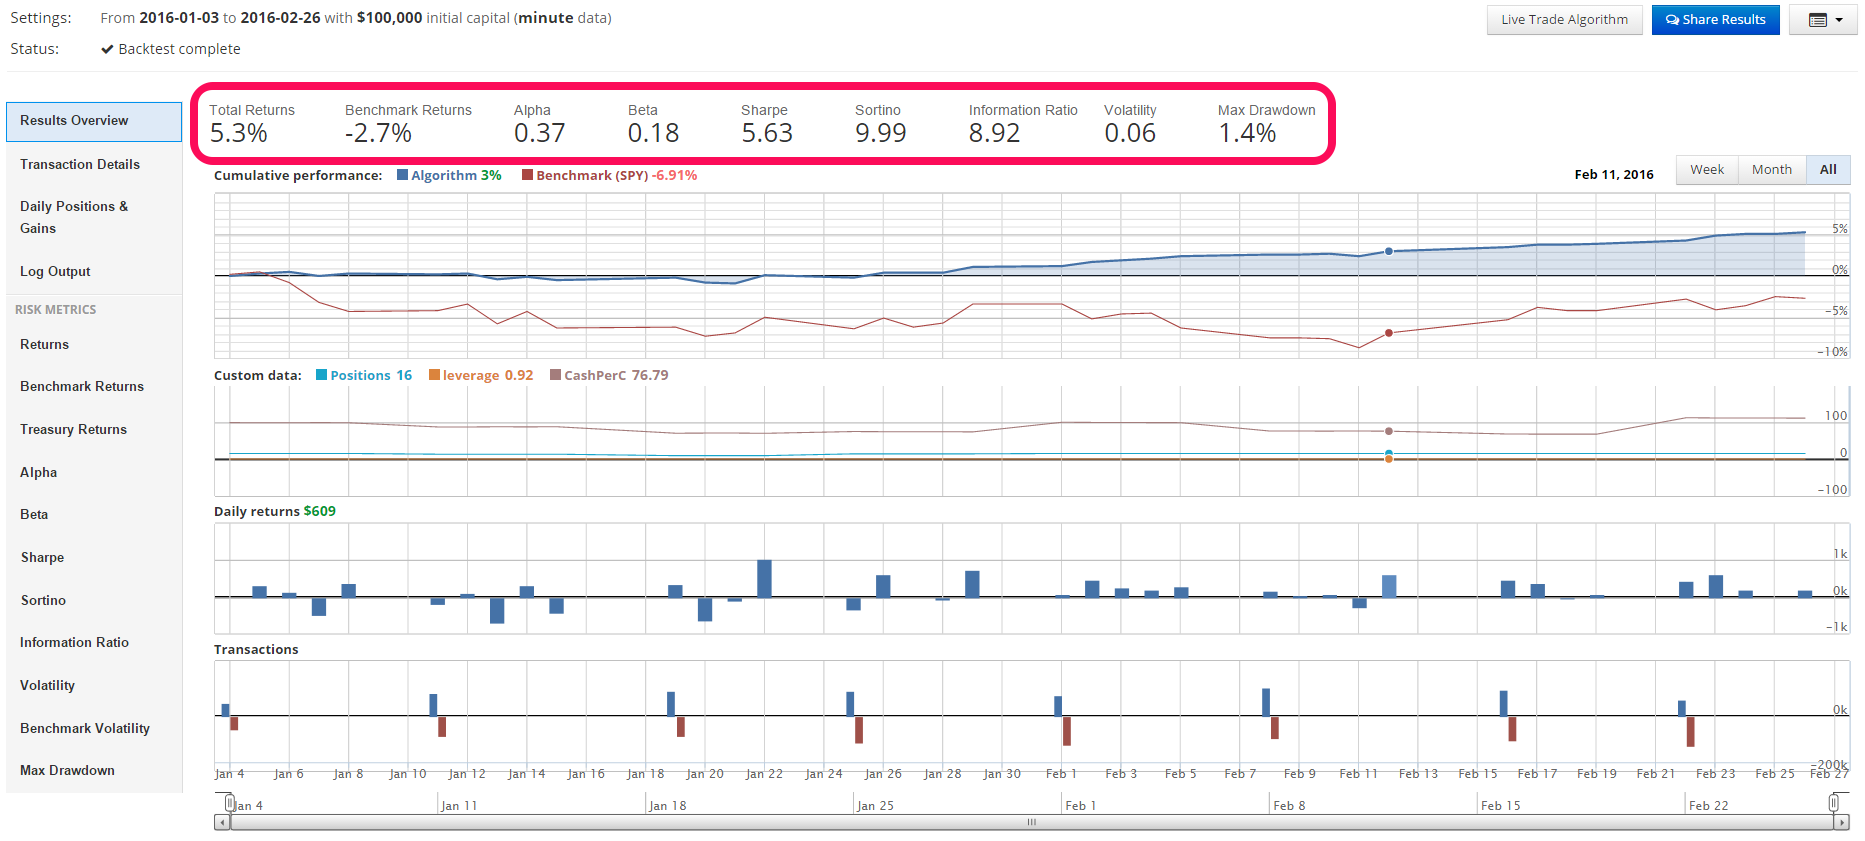
BACKTESTING THE IMPLIED VOLATILITY STRATEGY WITH QUANTOPIAN (2/27/16)
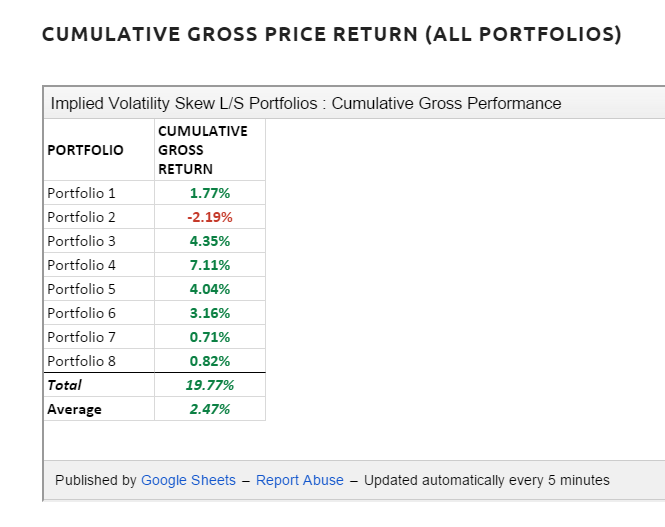
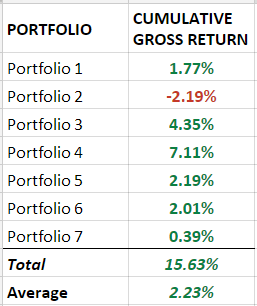
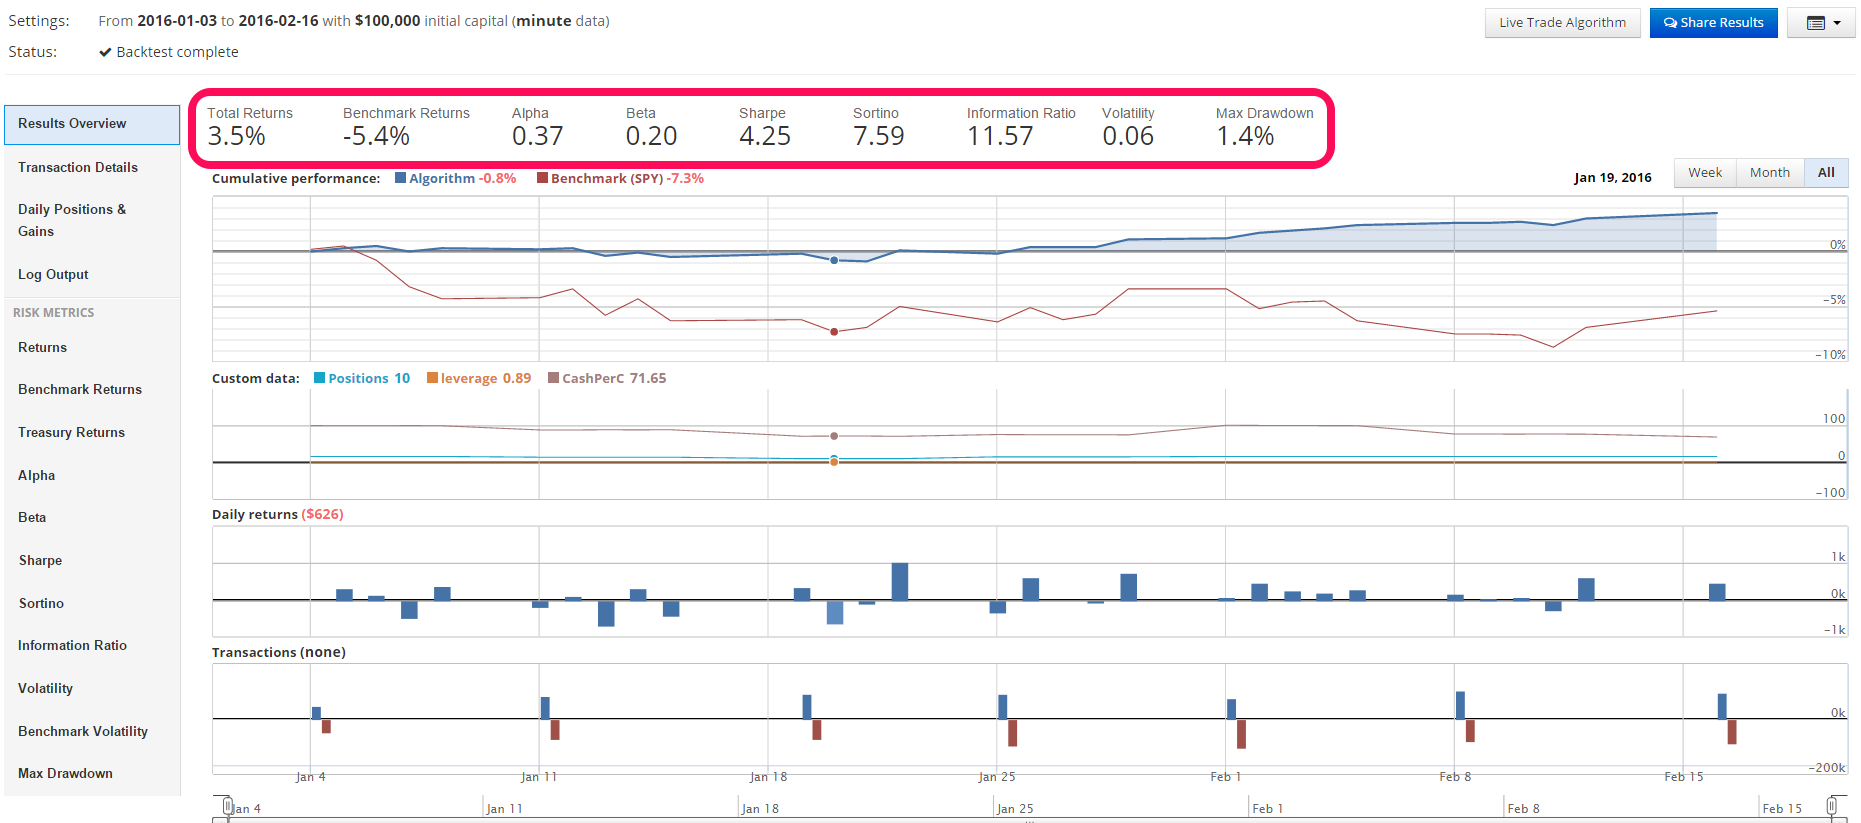
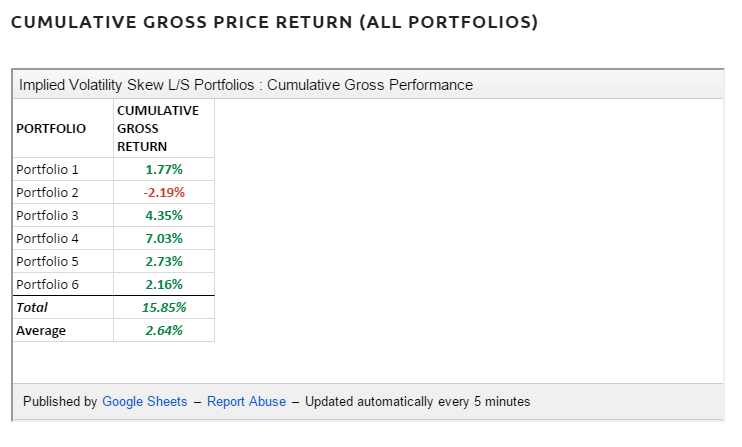
#block-yui_3_17_2_5_1456621692348_14798 .social-icons-style-border .sqs-svg-icon--wrapper { box-shadow: 0 0 0 2px inset; border: none; } FOR A DEEPER DIVE INTO ETF PERFORMANCE AND RELATIVE VALUE SUBSCRIBE TO THE ETF INTERNAL ANALYTICS PACKAGE HERE To see the origin of this series click here. To summarize, the strategy calculates a SKEW measure using ATM calls and OTM puts for a collection of ETF symbols. It then sorts the symbols into quintiles based on the SKEW factor. Using daily close/cl
READ MORE →